That pit in your stomach when you open your banking app. The racing heart when an unexpected bill arrives in the mail. The persistent hum of worry that follows you from your morning coffee to your midnight ceiling-staring sessions. Financial anxiety is more than just a fleeting concern about cash flow; for many, it is a chronic state of hyper-vigilance that impacts mental health, physical well-being, and daily decision-making.
If you find yourself constantly refreshing your balance or avoiding your financial statements entirely, you are not alone. Money is deeply tied to our sense of security and self-worth. However, managing this anxiety isn’t necessarily about accumulating more wealth—though that helps—but about changing your relationship with the money you have. By integrating mindful money habits into your daily routine, you can transition from a state of reactive panic to one of proactive calm.
In this guide, we will explore the psychology behind money worries, address why even high earners feel the pinch of anxiety, and provide actionable, mindfulness-based strategies to help you stop worrying about money and start living.
Understanding Financial Anxiety: It’s More Than Just Math
Financial anxiety, often colloquially referred to as “money anxiety disorder,” isn’t a formal clinical diagnosis in the DSM-5, but its effects are very real. It is characterized by excessive worry, fear, and stress regarding one’s financial situation. Unlike general stress, financial anxiety often triggers our “fight or flight” response. When you view a bill as a threat, your brain treats it like a predator in the wild.
According to the American Psychological Association (APA), money has consistently ranked as a top source of stress for Americans for over a decade. In recent surveys, nearly 72% of adults reported feeling stressed about money at least some of the time, with a significant portion reporting that their financial stress has increased over the past year. This stress can manifest physically as insomnia, headaches, and digestive issues, or emotionally as irritability and depression.
The Paradox of Money Anxiety When Well Off
A common misconception is that financial anxiety disappears once you reach a certain income bracket. However, “money anxiety when well off” is a frequent topic of discussion on platforms like Reddit and financial therapy forums. Why? Because anxiety is often rooted in scarcity mindset rather than actual scarcity.
If you grew up in a household where money was tight or unpredictable, your nervous system may have been “wired” to expect financial disaster, regardless of your current bank balance. This is often called “financial trauma.” High earners often suffer from “lifestyle creep”—the phenomenon where expenses rise to meet income—leaving them feeling just as vulnerable as they did when they earned less. To manage this, one must address the emotional triggers of spending and saving, not just the numbers on a spreadsheet.
The Science of Mindful Money Habits
Mindfulness is the practice of being present and fully engaged with whatever we are doing at the moment, free from distraction or judgment. When applied to finance, mindfulness helps us step out of the “shame spiral” and look at our finances with objective curiosity.
Most financial stress comes from two places: regretting the past (the debt you accumulated) or fearing the future (will I ever be able to retire?). Mindful money habits bring you back to the present: What is the healthiest choice I can make with my resources right now?
1. The “Financial Body Scan”
Before you check your bank balance or sit down to pay bills, perform a quick body scan. Notice where you are holding tension. Is your jaw clenched? Are your shoulders up by your ears? By acknowledging the physical sensation of anxiety before you look at the numbers, you create a “buffer” between your emotional reaction and your logical brain. This prevents the impulsive decision-making that often leads to “retail therapy” or total financial avoidance.
2. Mindful Spending: The 24-Hour Rule
One of the most effective ways to reduce buyer’s remorse and the subsequent anxiety it causes is the 24-hour rule. In an era of one-click shopping and digital wallets, the friction of spending has vanished. Reintroduce that friction by waiting a full day before making any non-essential purchase over $50.
During those 24 hours, ask yourself: “Does this purchase align with my values? Will this bring me long-term peace or a short-term dopamine hit?” Often, the urge to spend is a way to soothe an unrelated emotion. By identifying that emotion, you take the power away from the transaction.
Practical Daily Habits to Reduce Money Worry
Dealing with money anxiety requires a combination of emotional regulation and practical systems. When your finances are organized, your brain doesn’t have to work as hard to keep track of the “unknowns.” Developing financial discipline can help bridge the gap between feeling overwhelmed and feeling in control.
Automate Your Peace of Mind
Decision fatigue is a real contributor to anxiety. Every time you have to decide whether to save or spend, you are using willpower. Automating your finances removes the choice. Set up automatic transfers to your savings account and automated bill payments for your essentials. Knowing that your future self is being taken care of without you having to lift a finger provides a massive psychological safety net.
The “Money Date” Ritual
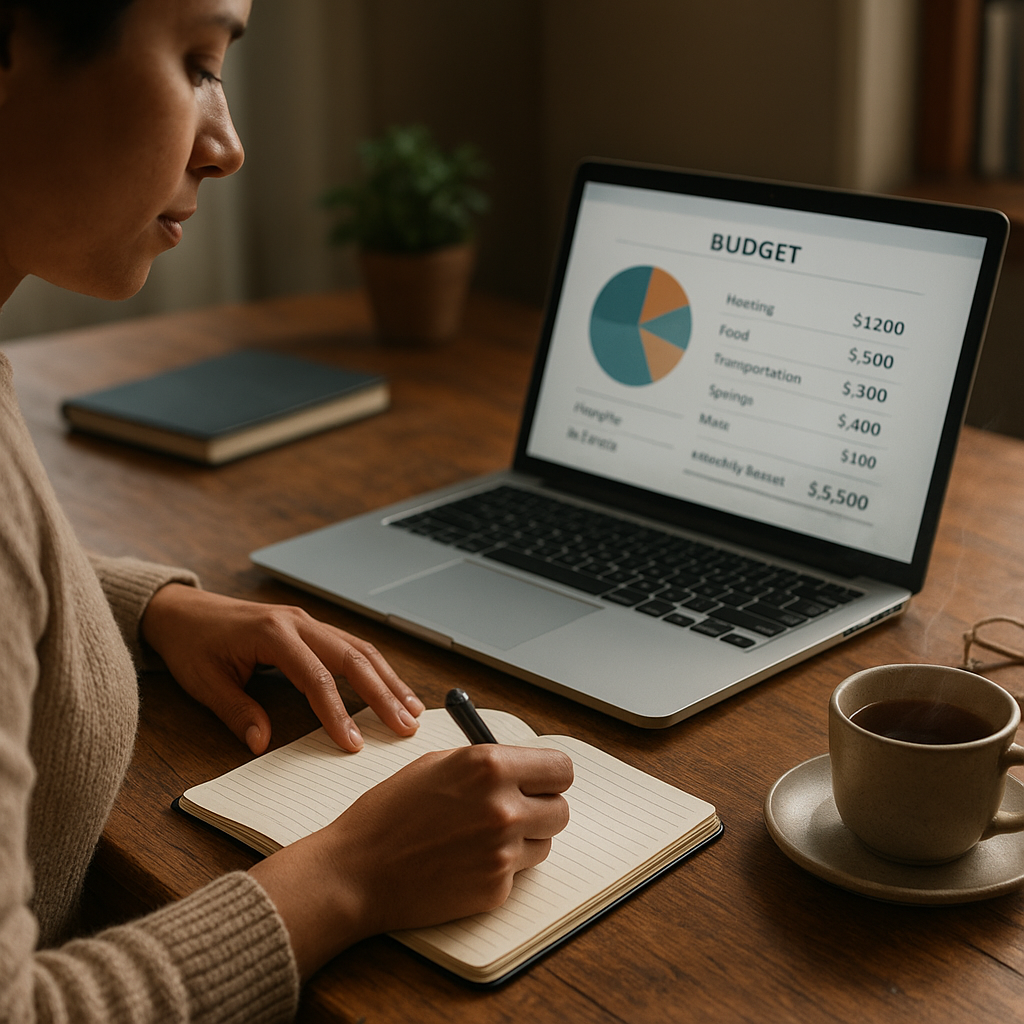
Avoidance is the fuel of anxiety. The longer you ignore a problem, the larger it grows in your imagination. To combat this, schedule a weekly “Money Date.” Make it pleasant: light a candle, pour a glass of wine or tea, and spend 20 minutes reviewing your accounts. Because this is a scheduled event, you can give yourself permission to not think about money the other six days of the week. This “containment” strategy is a powerful tool for those who find their minds wandering toward financial doom at all hours.
- Review transactions: Look for recurring subscriptions you no longer use.
- Check progress: Acknowledge how much closer you are to your savings goals.
- Practice gratitude: List three things your money allowed you to do this week (e.g., “I’m grateful my money paid for the electricity that keeps my home warm”).
Shifting from Scarcity to Abundance
To truly stop worrying about money and start living, you must confront the “scarcity mindset.” This is the belief that there is never enough, and that someone else’s gain is your loss. This mindset leads to hoarding behaviors, guilt over small joys (like buying a latte), and a constant sense of “falling behind.”
Reframing Your “Why”
Instead of viewing a budget as a set of restrictions, view it as a plan for empowerment. A budget isn’t telling you what you can’t do; it’s telling your money where to go so you can do what you love. If you value travel, your budget is a tool that ensures you have the funds for your next adventure. If you value security, your budget is a fortress you are building brick by brick.
Addressing “Comparison Culture”
Social media often exacerbates financial anxiety. We see curated highlights of other people’s vacations, new cars, and home renovations, leading to “status anxiety.” Remember that you are seeing their “outside” while feeling your own “inside.” Practice digital mindfulness by unfollowing accounts that trigger feelings of inadequacy or envy.
When Financial Anxiety Becomes Overwhelming
While mindfulness and daily habits are effective for situational stress, sometimes the weight of money worry requires professional intervention. If your financial anxiety is leading to panic attacks, severe depression, or an inability to function at work or in your relationships, it may be time to seek help.
Financial therapy is a growing field that combines financial planning with psychological counseling. It addresses the “why” behind our money behaviors. Additionally, non-profit credit counseling agencies can help you create a debt management plan, which often provides the immediate relief of having a structured path forward.
Actionable Tips for Immediate Relief
If you are feeling a surge of financial anxiety right now, try these five steps to ground yourself:
- The 5-4-3-2-1 Technique: Name 5 things you can see, 4 you can touch, 3 you can hear, 2 you can smell, and 1 you can taste. This pulls you out of the “financial future” and back into the physical present.
- Write it down: Externalize your worries. Often, the “monster” of debt or an upcoming expense is much more manageable on paper than it is in the echoes of your mind.
- Focus on “The Next Right Thing”: You don’t have to fix your entire financial life today. You just have to make one good choice today. Maybe it’s packing a lunch instead of buying one, or simply opening that one envelope you’ve been avoiding.
- Unplug from Financial News: Constant exposure to market volatility and inflation headlines can create a sense of impending doom. Limit your news intake to once a day. For some, exploring AI money management tools can also help automate decisions and reduce the stress of constant monitoring.
- Physical Movement: Stress is stored in the body. A brisk 10-minute walk can help metabolize the cortisol and adrenaline produced by financial worry.
Conclusion: Finding Your Financial Center
Managing financial anxiety is a journey, not a destination. There will be months where the budget is tight and the stress feels heavy, and there will be seasons of abundance where you feel secure. The goal of mindful money habits is not to reach a state where you never think about money, but to reach a state where money no longer controls your emotional temperature.
By acknowledging the psychological roots of your stress, implementing practical systems like automation, and practicing daily mindfulness, you can reclaim your mental space. Remember that your worth is not your net worth. You are more than your debt, your credit score, or your salary. By treating yourself with compassion and staying present in your financial decisions, you can build a life that feels rich in every sense of the word.
Start small. Pick one habit—perhaps the 24-hour rule or the weekly money date—and commit to it for thirty days. As you gain confidence in your ability to manage the present, the fear of the future will naturally begin to fade.